


Page 16 - Policy Economic Report -August 2026
P. 16
POLICY AND ECONOMIC
    OIL & GAS MARKET

The ASEAN rebound was particularly notable. Manufacturing output across the region accelerated to
its fastest pace since February, led by Thailand and Vietnam, while Indonesia recorded the largest monthly
improvement. The improvement followed the easing of some supply-chain disruptions associated with
energy flows. This suggests that manufacturing activity in Southeast Asia is proving relatively responsive
to the normalisation of supply conditions and remains an important part of the ongoing reconfiguration
of global production networks.

By contrast, North American manufacturing activity weakened. US factory growth deteriorated while
Mexican output fell further, although Canada continued to expand. In Europe, manufacturing activity
improved, with Germany recording its strongest expansion in more than four years and the eurozone
registering its fastest manufacturing growth since March 2022. Japan remained a standout performer,
with manufacturing supported by a weaker yen and strong demand for technology equipment.

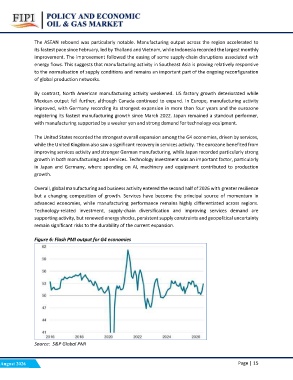
The United States recorded the strongest overall expansion among the G4 economies, driven by services,
while the United Kingdom also saw a significant recovery in services activity. The eurozone benefited from
improving services activity and stronger German manufacturing, while Japan recorded particularly strong
growth in both manufacturing and services. Technology investment was an important factor, particularly
in Japan and Germany, where spending on AI, machinery and equipment contributed to production
growth.

Overall, global manufacturing and business activity entered the second half of 2026 with greater resilience
but a changing composition of growth. Services have become the principal source of momentum in
advanced economies, while manufacturing performance remains highly differentiated across regions.
Technology-related investment, supply-chain diversification and improving services demand are
supporting activity, but renewed energy shocks, persistent supply constraints and geopolitical uncertainty
remain significant risks to the durability of the current expansion.

Figure 6: Flash PMI output for G4 economies

                   Source: S&P Global PMI  Page | 15

August 2026

