


Page 15 - Policy Economic Report -August 2026
P. 15
POLICY AND ECONOMIC
                 OIL & GAS MARKET

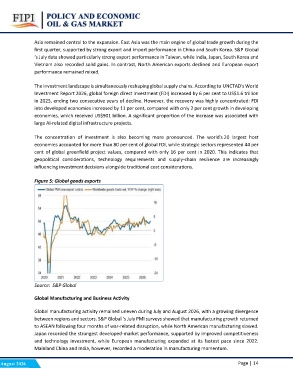
             Asia remained central to the expansion. East Asia was the main engine of global trade growth during the
             first quarter, supported by strong export and import performance in China and South Korea. S&P Global
             ‘s July data showed particularly strong export performance in Taiwan, while India, Japan, South Korea and
             Vietnam also recorded solid gains. In contrast, North American exports declined and European export
             performance remained mixed.

             The investment landscape is simultaneously reshaping global supply chains. According to UNCTAD's World
             Investment Report 2026, global foreign direct investment (FDI) increased by 6 per cent to US$1.6 trillion
             in 2025, ending two consecutive years of decline. However, the recovery was highly concentrated: FDI
             into developed economies increased by 11 per cent, compared with only 2 per cent growth in developing
             economies, which received US$901 billion. A significant proportion of the increase was associated with
             large AI-related digital infrastructure projects.

             The concentration of investment is also becoming more pronounced. The world's 20 largest host
             economies accounted for more than 80 per cent of global FDI, while strategic sectors represented 44 per
             cent of global greenfield project values, compared with only 16 per cent in 2020. This indicates that
             geopolitical considerations, technology requirements and supply-chain resilience are increasingly
             influencing investment decisions alongside traditional cost considerations.

             Figure 5: Global goods exports

             Source: S&P Global

             Global Manufacturing and Business Activity

             Global manufacturing activity remained uneven during July and August 2026, with a growing divergence
             between regions and sectors. S&P Global ‘s July PMI surveys showed that manufacturing growth returned
             to ASEAN following four months of war-related disruption, while North American manufacturing slowed.
             Japan recorded the strongest developed-market performance, supported by improved competitiveness
             and technology investment, while European manufacturing expanded at its fastest pace since 2022.
             Mainland China and India, however, recorded a moderation in manufacturing momentum.

August 2026  Page | 14

