


Page 28 - Policy Economic Report - September 2026
P. 28
POLICY AND ECONOMIC
                    OIL & GAS MARKET

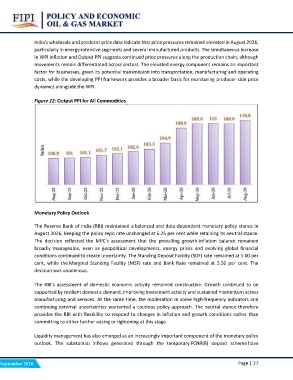
                India's wholesale and producer price data indicate that price pressures remained elevated in August 2026,
                particularly in energy-intensive segments and several manufactured products. The simultaneous increase
                in WPI inflation and Output PPI suggests continued price pressures along the production chain, although
                movements remain differentiated across sectors. The elevated energy component remains an important
                factor for businesses, given its potential transmission into transportation, manufacturing and operating
                costs, while the developing PPI framework provides a broader basis for monitoring producer-side price
                dynamics alongside the WPI.

                Figure 12: Output PPI for All Commodities

                Monetary Policy Outlook

                The Reserve Bank of India (RBI) maintained a balanced and data-dependent monetary policy stance in
                August 2026, keeping the policy repo rate unchanged at 5.25 per cent while retaining its neutral stance.
                The decision reflected the MPC's assessment that the prevailing growth-inflation balance remained
                broadly manageable, even as geopolitical developments, energy prices and evolving global financial
                conditions continued to create uncertainty. The Standing Deposit Facility (SDF) rate remained at 5.00 per
                cent, while the Marginal Standing Facility (MSF) rate and Bank Rate remained at 5.50 per cent. The
                decision was unanimous.

                The RBI's assessment of domestic economic activity remained constructive. Growth continued to be
                supported by resilient domestic demand, improving investment activity and sustained momentum across
                manufacturing and services. At the same time, the moderation in some high-frequency indicators and
                continuing external uncertainties warranted a cautious policy approach. The neutral stance therefore
                provides the RBI with flexibility to respond to changes in inflation and growth conditions rather than
                committing to either further easing or tightening at this stage.

                Liquidity management has also emerged as an increasingly important component of the monetary policy
                outlook. The substantial inflows generated through the temporary FCNR(B) deposit scheme have

September 2026  Page | 27

